XRP Ledger lending is gaining validator assist, however approval remains to be pending. The proposed credit score market shifts consideration from collateral to underwriting.
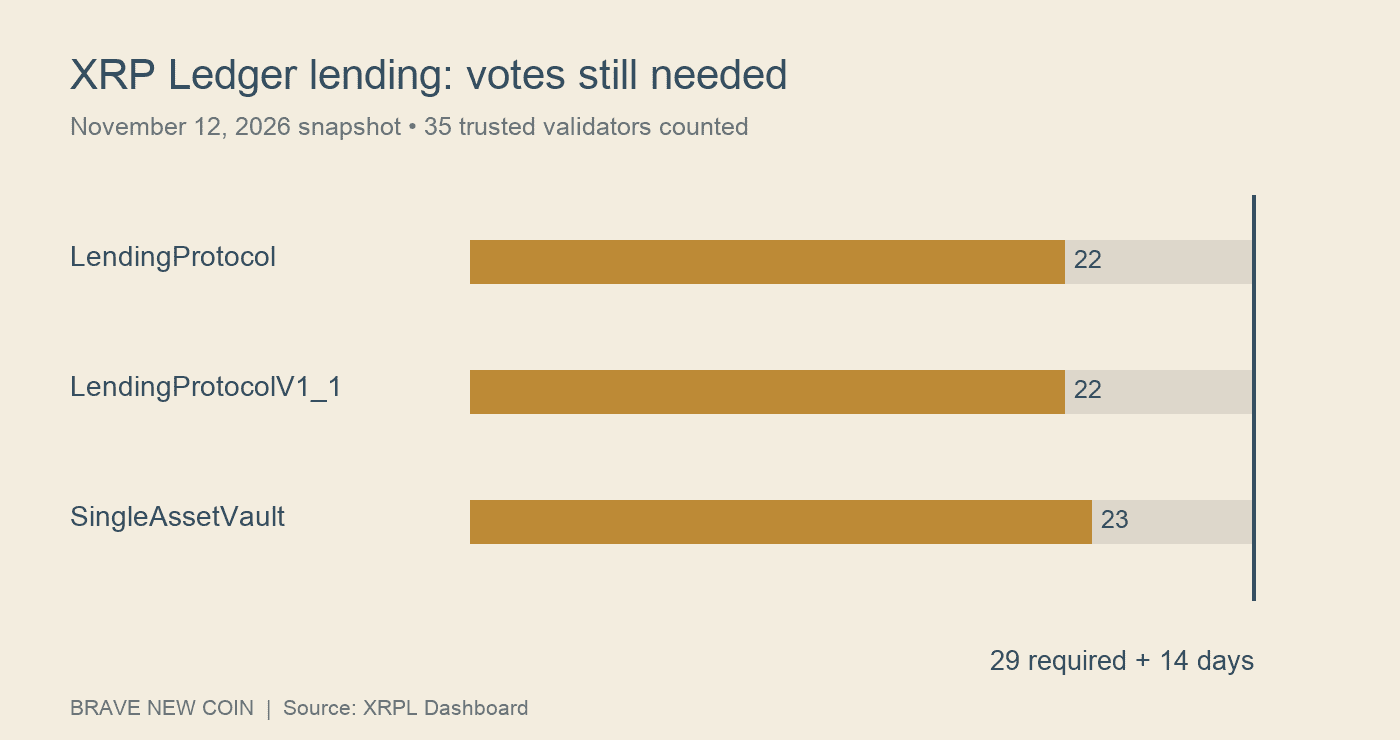
XRP Ledger’s proposed lending system is gaining validator assist, however the hole between a promising improve and a usable credit score market stays important. The lending modification has 22 supporting votes towards a present requirement of 29, whereas the vault expertise it wants has 23.
The November 12 governance snapshot places the undertaking nearer to approval than in mid-October. It additionally establishes an essential restrict on the joy: lending has not activated, and its two-week approval countdown has not began.
XRP Ledger lending votes climb, however approval is pending
The unbiased XRPL Dashboard snapshot data 22 of 35 trusted validators supporting LendingProtocol and LendingProtocolV1_1, with 23 supporting SingleAssetVault. CoinDesk’s November 12 report put the sooner October 19 counts at 19 for lending and 21 for vaults.
That’s progress, moderately than a launch date. The lending proposals nonetheless want seven extra supporting votes on that validator set, and the vault modification wants six. Counts can transfer in both course earlier than activation.
The community’s amendment documentation says: “Amendments should preserve two weeks of assist from greater than 80% of trusted validators to be enabled.” With 35 counted validators, strictly greater than 80% means 29 votes. Reaching 28 would depart the proposals brief.
The 2-week rule prevents a short burst of assist from immediately altering the ledger. It additionally implies that a forecast launch date can not merely be calculated from right this moment’s vote depend. The required majority should first type after which persist.
What the lending system would truly do
The XLS-66 lending specification describes fixed-term loans funded by means of pooled belongings. A dealer would prepare credit score for debtors, with the ledger recording the mortgage and its funds. Debtors wouldn’t have to submit the on-chain collateral acquainted from many current crypto lending markets.
That modifications the place lenders should search for safety. The specification says the design “depends on off-chain underwriting and danger administration.” Assessing a borrower’s skill to repay subsequently stays a human and institutional job even when the settlement is recorded on a blockchain.
First-loss capital can soak up a part of a default loss the place supplied, nevertheless it doesn’t remove credit score danger. A lender nonetheless wants to know the dealer, borrower choice, phrases and accessible loss safety. A clear document of a mortgage is efficacious; it’s not proof that the mortgage might be repaid.
For establishments, the attraction is the opportunity of combining typical credit score evaluation with ledger-based origination and servicing. That would cut back some coordination work with out turning each borrower into an overcollateralised crypto dealer. Whether or not it produces a commercially helpful market will depend upon the contributors and the phrases they provide.
Why the vault modification issues
The separate single-asset vault specification units out how depositors can pool one asset and obtain shares representing their curiosity. Lending makes use of that pool as its supply of funds, so approving the mortgage mechanism with out the mandatory vault infrastructure wouldn’t full the system.
The vault idea separates the cash pool from particular person loans. That makes the connection between deposits, excellent credit score and withdrawals essential. Buyers ought to look at how a specific product handles funds dedicated to loans moderately than assuming a vault share is equal to right away accessible money.
These are product-design questions, not merely software program questions. A ledger can implement accounting guidelines whereas the underlying credit score stays illiquid or topic to default. Larger promised returns would must be assessed towards these dangers moderately than handled as an automated good thing about shifting finance on-chain.
Builders are nonetheless refining the design
Work continues alongside the governance course of. A public development proposal proposes one other lending modification, LendingProtocolV1_2, addressing transaction sequencing when a mortgage is opened. It remained an open improvement proposal when checked for this report, moderately than an activated community characteristic.
That distinction issues as a result of software program proposals, launched code and enabled amendments signify totally different levels. A characteristic can exist in public improvement with out being accessible for reside borrowing. Conversely, a patch to supporting code doesn’t by itself authorise the total lending market to start working.
For readers following XRP as an funding, governance progress is a concrete improvement to observe. It’s extra informative than a broad declare that institutional adoption is inevitable. It additionally provides no dependable formulation for translating a validator vote right into a token-price goal.
BNC’s protection of David Schwartz’s personal XRP holdings issues a separate query about a person’s portfolio. Protocol adoption ought to be assessed by means of implementation and utilization proof moderately than inferred from one holder’s shopping for or promoting.
What would flip this right into a stronger XRP catalyst?
The following significant milestones are a sustained validator majority, activation of the required amendments and precise lending exercise. After launch, the standard of debtors, efficiency of loans and remedy of defaults would supply a greater take a look at of the system than a headline deposit whole alone.
The connection to XRP demand can even want proof. A credit score platform can assist ledger exercise with out each mortgage essentially requiring a speculative buy of XRP. Buyers ought to distinguish community utility, the asset utilized in a specific vault and the financial profit that ultimately reaches token holders.
For now, the improve is an advancing proposal with seen numbers to trace. Its strongest promise is a brand new credit score mechanism. Its largest unanswered query is whether or not contributors can handle extraordinary lending danger as fastidiously as builders handle the ledger guidelines.
Jason Jones Jason Jones Read More