JPMorgan and DBS have linked their tokenized deposit networks for round the clock greenback transfers. The launch reveals banks placing blockchain to work, whereas a Saturday upkeep window reveals the place the older system nonetheless issues.
JPMorgan and DBS have linked their blockchain deposit networks so institutional shoppers can transfer tokenized U.S. {dollars} between Singapore and the USA across the clock, together with weekends.
The November 16 launch announcement names Ant Worldwide as the primary shopper. It’s a concrete transfer from planning to business availability for a type of digital cash that retains banks on the centre of the transaction.
The attraction is simple: companies function throughout time zones even when standard banking processes pause. However the service additionally exposes a boundary within the always-on promise—transferring cash between JPMorgan’s legacy deposit accounts and blockchain accounts nonetheless has a Saturday interruption.
What JPMorgan and DBS have really launched
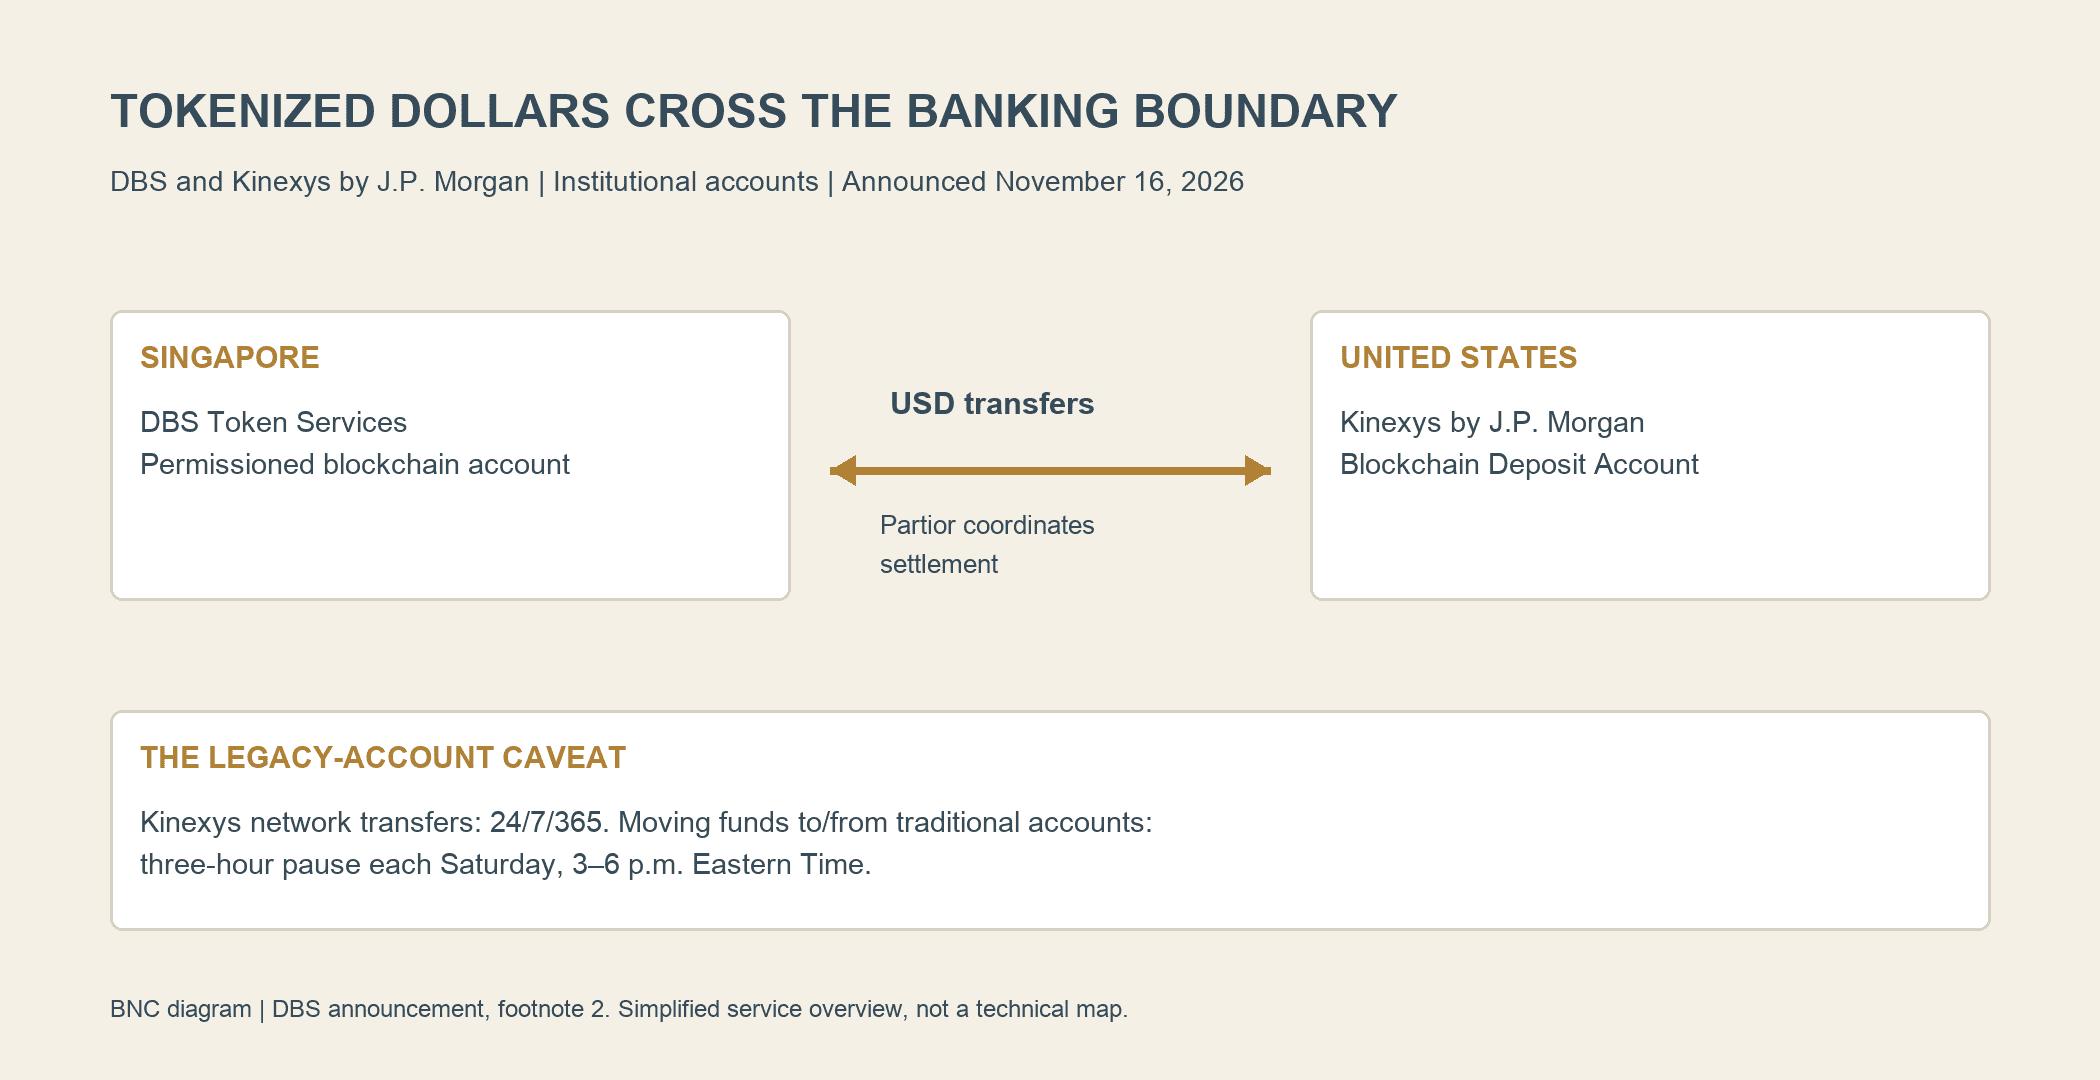
The hyperlink joins DBS Token Providers with Kinexys by J.P. Morgan’s account-based permissioned deposit community. Partior coordinates settlement. The said use case is institutional greenback liquidity between accounts within the two markets.
Rachel Chew, DBS’s chief working officer and co-head of digital property for world transaction companies, stated tokenized cash was transferring in direction of “delivering stay tangible worth for shoppers.”
The announcement’s footnote qualifies the working hours. Transfers inside the Kinexys blockchain account community run repeatedly, however transferring funds between these accounts and conventional demand deposit accounts pauses from three p.m. to six p.m. Japanese Time every Saturday. DBS says an enhancement is being developed.
Why the account boundary issues
For a treasury workforce, cash already contained in the related community and cash nonetheless sitting in a traditional account are completely different operational beginning factors. An obtainable switch route is beneficial provided that the funds can attain it when wanted.
Contemplate a hypothetical enterprise that expects a weekend funding requirement. Holding appropriate liquidity within the supported account beforehand may make the brand new connection helpful. Leaving every thing exterior it till the upkeep window would elevate a unique query.
That doesn’t negate the service’s usefulness. It reveals why corporations have to assess the entire cost journey: funding, switch, receipt and the recipient’s capacity to make use of the stability. Pace in a single stage can not reply each query concerning the others.
Likewise, a switch finishing throughout this hyperlink doesn’t set up that each unrelated provider can obtain a direct standard financial institution cost. Eligibility, account entry and onward cost preparations stay related.
A year-old framework turns into a working connection
The banks’ November 2025 framework announcement described plans to attach their separate on-chain ecosystems. On the time, every already supplied round the clock capabilities inside its personal surroundings.
The proposed subsequent step was exchangeability and settlement throughout the 2 programs, with ambitions spanning public and permissioned blockchains. The newly introduced service needs to be judged on its specified permissioned-account connection, fairly than assuming each a part of that broader ambition is now obtainable.
That is the interoperability drawback in sensible phrases. A quick community inside one financial institution has restricted attain if clients can not readily transact with one other financial institution’s community. Connecting establishments may be extra helpful than making an already fast inside switch barely sooner.
Tokenized deposits hold the financial institution within the image
DBS describes Token Services as a set of blockchain banking capabilities overlaying programmable worth transfers, liquidity administration and cost controls. Its proposition is an extension of banking companies utilizing tokenization and good contracts.
A tokenized financial institution deposit stays a declare related to a checking account. It differs from merely buying a freely circulating cryptocurrency for a private pockets. The related questions embody which establishment owes the cash, who could take part and the way transfers are ruled.
For stablecoin issuers, that creates competitors over a specific job: transferring digital greenback worth when clients want it. It doesn’t imply one launch replaces the various makes use of of public-chain stablecoins or creates demand for each blockchain token.
The business contest will flip partly on attain. A company service may be engaging inside an accepted banking relationship whereas serving a unique buyer from somebody in search of an open wallet-to-wallet cost.
For an establishment selecting between these routes, the helpful comparability is complete value, availability and operational match. A well-known financial institution relationship may matter as a lot because the underlying ledger know-how.
Singapore’s wider plan consists of AI funds
The Monetary Authority of Singapore’s Project BLOOM units out a wider effort to enhance home and cross-border settlement. It consists of regulated stablecoins and tokenized commercial-bank cash, alongside interoperability and programmable controls.
Its focus areas additionally embody funds by AI brokers inside predefined limits and safeguards. That could be a coverage and improvement path, not a declare that the brand new DBS–JPMorgan hyperlink has already enabled autonomous shopper spending.
BNC’s report on AI agents paying for computing with Bitcoin examined one other route in direction of automated transactions. Collectively, the developments present why cost infrastructure issues to AI in addition to finance: software program wants each authority to spend and a solution to settle.
The following check for the banks is sustained buyer utilization, broader connectivity and fewer interruptions on the boundaries. The launch gives a particular new greenback route. Its significance will develop if corporations can use it reliably as a part of on a regular basis money administration.
Jason Jones Jason Jones Read More